The cost of living on a boat comes down to five line items: the berth, insurance, maintenance, fuel and utilities, and the surprise fund. Which of those dominates depends almost entirely on where you keep the boat and how often you move it. A liveaboard on a mooring buoy in a quiet river town spends in a different universe from one on a dockwall in a city marina.
What surprises most first-time liveaboards is not the monthly bill. It is the shape of it. On land, rent arrives once a month and is predictable. Aboard, the steady costs are smaller than people expect and the lumpy ones — a failed watermaker, a bent propeller shaft, an insurance renewal — are larger. The honest answer to "how much" is the one the dictionaries give: Cambridge Dictionary defines "much" as "a great quantity or degree", which is to say the number moves. What follows is the structure of the budget, so you can fill in your own figures.
What does the berth actually cost?
The berth is usually the biggest steady line, and it is the one with the widest spread. Marinas price by boat length, and the price per metre rises sharply with location: a metropolitan marina near a city centre can charge several times what a working harbour or a river club charges for the same footprint. Many marinas also charge liveaboards a premium over the standard rate, because a resident uses more of everything — power, water, pump-out, showers, staff time.
Alternatives exist, and each trades money for something. A mooring buoy or an anchor berth costs little or nothing, but you give up shore power, easy water top-ups and a short walk to the shower block. Living at anchor is genuinely cheap and genuinely work, as anyone who has run a day at anchor around tank levels and dinghy runs will confirm. A harbour with a dinghy dock and a laundromat can be a workable middle ground.
Before you sign a berth contract, ask three questions in writing: what the annual increase policy is, whether liveaboard status is included or billed separately, and what happens in a storm or a haul-out. A berth that looks cheap until the winter surcharge arrives is not cheap.
Insurance: the line you cannot skip
Insurers price on the boat's value, its age, the owner's experience and — decisively — where the boat keeps and cruises. A vessel kept in a hurricane-exposed region pays for that exposure, and some policies require a documented haul-out plan or a named storm-season zone. Older boats can face survey requirements before a policy binds at all.
The practical point: get the quote before you commit to the boat, not after. Insurance can quietly disqualify a purchase that looked affordable on paper, and the excess — the portion you pay yourself on any claim — is part of your real risk budget, not a detail.
Maintenance: the steady drip and the sudden drop
Maintenance comes in two shapes and both belong in the budget. The steady drip is consumables: engine oil and filters, antifouling paint on a haul-out cycle, anodes, canvas, sealants. The sudden drop is the failure — a raw-water pump, a chartplotter, a rigging turnbuckle — that arrives without an appointment. Salt water is patient and unsentimental; everything on the boat is either being slowly consumed or is waiting to be.
A common discipline among liveaboards is to set a fixed share of income aside every month for the boat whether or not anything is broken, and to let the fund carry over. The years you spend nothing are funding the year you replace the standing rigging. Systems that touch water deserve special attention: our guide to fresh water at sea covers why tanks, watermakers and pumps are the maintenance category that most shapes daily life. For related coverage, see Fresh water at sea: tanks, watermakers and why showers are short.
Fuel, power and the daily running costs
If the boat moves under power, fuel becomes a real line and it scales with speed. Displacement hulls burn dramatically less at hull speed than planing hulls do at cruising speed, which is why a slow sailboat crossing is a different financial proposition from a fast motor yacht doing the same route. Under sail, fuel use drops toward the marina-approach minimum — the wind is the only free propulsion the industry offers.
Power at the dock is usually metered or flat-rated; at anchor it comes from solar, a wind generator, the engine's alternator or a generator that burns the same fuel as the main engine. Food is the pleasant surprise: a liveaboard's galley is small, which disciplines the shopping. Our piece on cooking in a seaway makes the point that a two-burner stove and a small oven, used well, feed a crew properly — and the provisioning run, covered in how a provisioning run actually works, is where the food budget is won or lost.
What this means: building your own budget
Our analysis of how liveaboard budgets actually behave is this: the fixed lines are knowable in an afternoon, and the variable ones are a habit, not a number. Before you move aboard, price the berth in writing, get an insurance quote for the specific boat and location, and list the boat's known deferred maintenance from the survey. Those three documents are the real answer to the cost question for your boat, not anyone else's.
Then add the habits. A monthly set-aside for the surprise fund. A haul-out on the calendar with the antifouling and anode budget attached. A fuel log for the first season, because your own burn rate beats any rule of thumb. Liveaboards who keep receipts rarely get ambushed; the ones who don't usually tell the same story about the pump that failed in high season.
One more line people forget: the exit. Boats sell, and the selling costs — broker commission or your own time, a survey for the buyer, a haul-out for the showing — belong in the lifetime cost of the decision, not in a separate mental account.
Is it cheaper than living ashore?
Sometimes, but not automatically. A liveaboard on a modest boat, on a mooring, in a low-cost harbour, with the discipline to maintain it, can spend less than the rent on a small apartment in the same town. The same person on a larger boat in a premium marina, with a payment on the loan, will spend more. The boat is a home and a machine at once; the machine part is what makes the comparison honest. Cheap is a choice of boat and berth, not a property of boats in general.
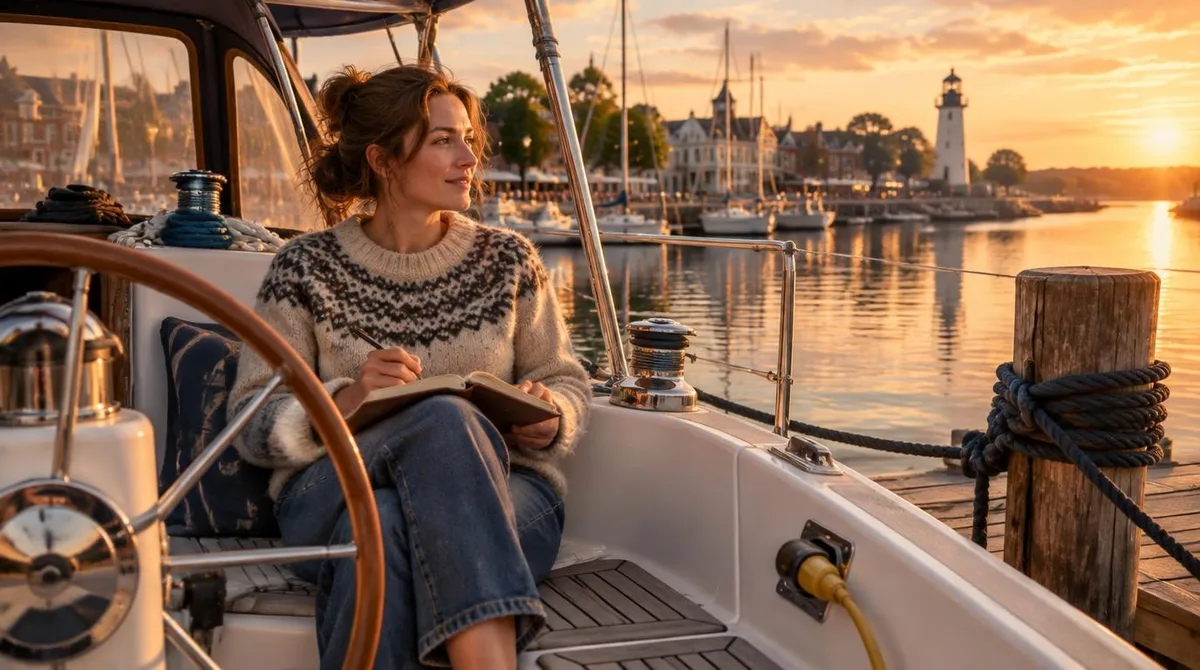
The trade is not only financial. You are buying proximity to the water, a smaller footprint and a life where the weather is news. You are also buying pumps, humidity and a shower timed to the tank level. Readers weighing the move may find it useful to read what the daily rhythm actually looks like in life aboard a sailboat before pricing it.
The bottom line on boat budgeting
What the evidence of how liveaboards actually spend establishes is a structure, not a figure: berth, insurance, maintenance, fuel and utilities, surprise fund, in roughly that order of weight, with the first and third trading places depending on where you keep the boat. What remains unknown until you price your own boat, your own harbour and your own cruising pattern is the total. Get those three quotes and the budget stops being a rumour and becomes a plan.